Volatility forecasting and options.
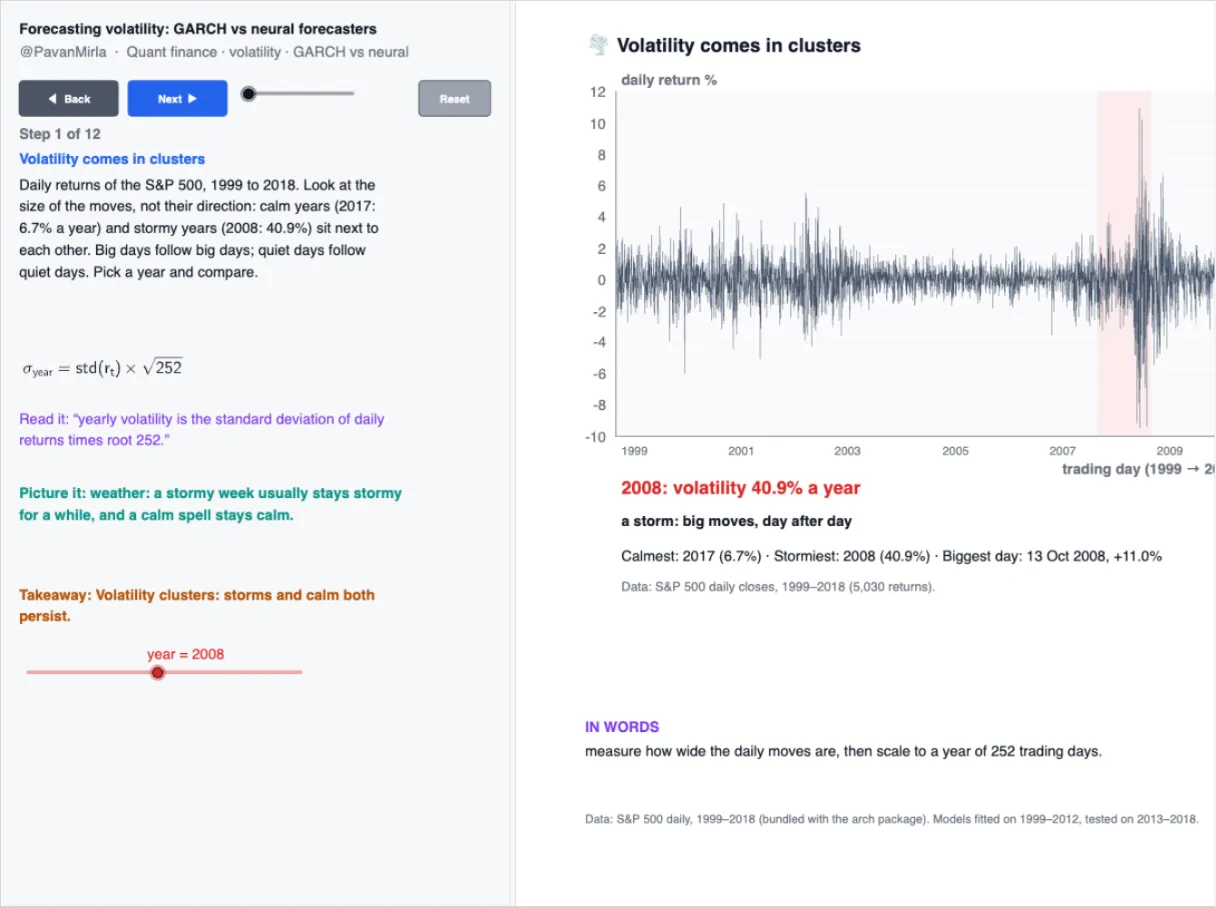
Forecast volatility first: GARCH and HAR against neural forecasters and the VIX, scored with QLIKE and audited for leaks, then turned into a position size.
Then take it to options: from Black–Scholes σ to an arbitrage-free SPX surface, AI with guardrails, and Greeks tested on real trading days.
This path is the course material for the Advanced Volatility Forecasting: Classical vs AI bootcamp. Education, not financial advice.
Explore next
- VF001 · Forecasting volatility
- VF002 · Realised, forecast and implied volatility
- VF003 · QLIKE
- VF004 · Audit discipline
- VF005 · Volatility targeting
- VF006 · Volatility for options
- VF007 · Arbitrage-free volatility surfaces
- VF008 · Greeks from the surface
Stories, illustrations, and interactive mini lessons. Ask a question.