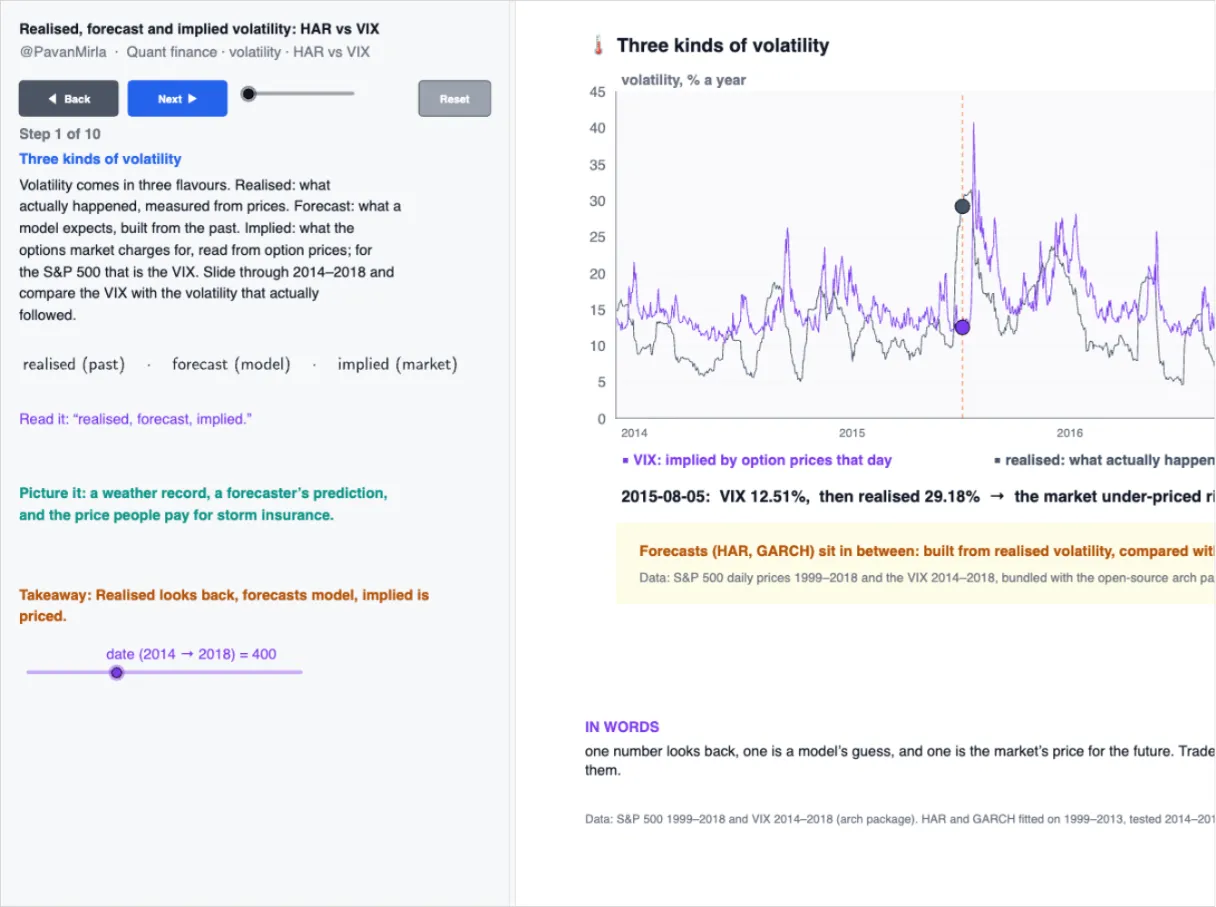
Realised, forecast and implied volatility
VF002 · Volatility forecasting and options · Lesson 2 of 8. Ten interactive steps, each with its own guided explanation.
Realised, forecast and implied vol side by side. HAR’s daily/weekly/monthly cascade against the VIX, and what the gap (the variance risk premium) pays.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
- Volatility forecasting and options: the eight-lesson path
- Advanced Volatility Forecasting: Classical vs AI bootcamp
Stories, illustrations, and interactive mini lessons. Ask a question.