Advanced Volatility Forecasting: Classical vs AI
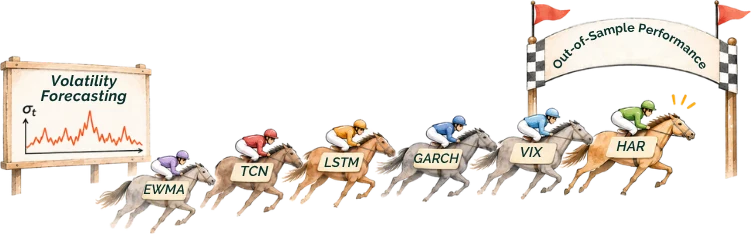
Classical econometrics vs deep learning. Benchmarked out of sample, then deployed with AI agents. We build EWMA, GARCH and HAR, derive the maths behind them, then test TCNs, LSTMs and transformers the same way on data they have never seen, and wire the winner into AI agents as a secure MCP tool.
Why it matters: every risk number starts with a volatility forecast. It drives VaR and risk limits, option pricing and hedging, position sizing and volatility targeting, and model validation. The simple HAR model is hard to beat on one daily series; we show why, and where deep learning does win.
Seven modules: the maths of volatility; classical baselines and implied volatility; the right objective (QLIKE); validation without leaks; deep learning architectures; from forecast to position; deployment with AI agents.
Built for people whose P&L depends on volatility: quant funds (research, risk and tech together), systematic and discretionary portfolio managers, options and volatility traders, quant researchers and developers, and risk managers and model validators. Free 45-minute Lunch & Learn on Zoom, then a live bootcamp priced per team, on Zoom or on-site. Questions: office@21ifm.com.
This is education about mathematics, models and their assumptions, not financial advice.
Explore next
- Quant Finance and AI Bootcamp
- Volatility: the human-scale measure of risk (MF007)
- Learning from forecasts in markets (ML016)
- Ronald Fisher and the idea of likelihood
Stories, illustrations, and interactive mini lessons. Ask a question.