Volatility for options
VF006 · Volatility forecasting and options · Lesson 6 of 8. Twelve interactive steps, each with its own guided explanation.
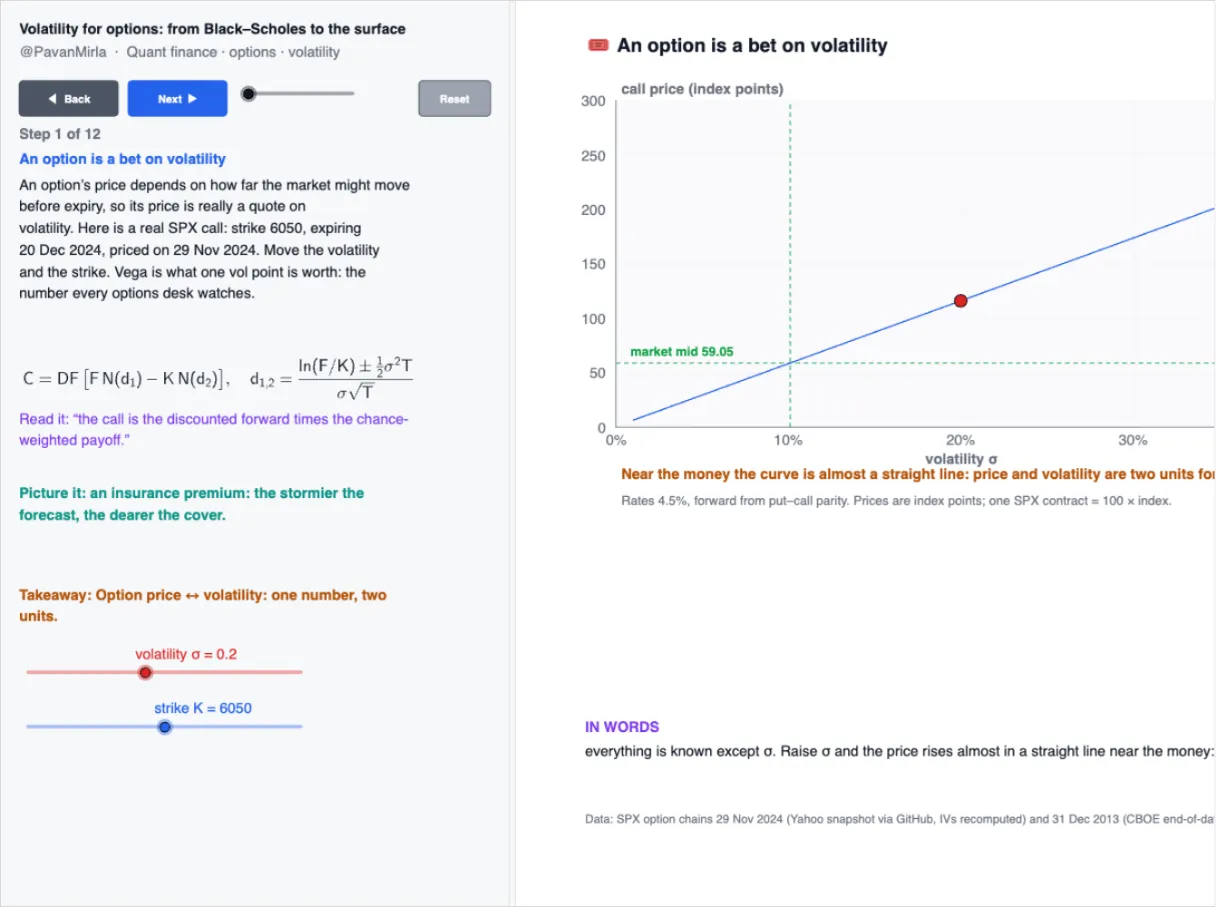
From Black–Scholes σ to the full SPX implied-vol surface on real chains: smiles, skews, term structure, the Fed-day bump, and where forecasting fits.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
- Volatility forecasting and options: the eight-lesson path
- Advanced Volatility Forecasting: Classical vs AI bootcamp
Stories, illustrations, and interactive mini lessons. Ask a question.