Volatility in factor models
VF006 · Volatility forecasting · Lesson 6 of 13. Eight interactive steps, each with its own guided explanation.
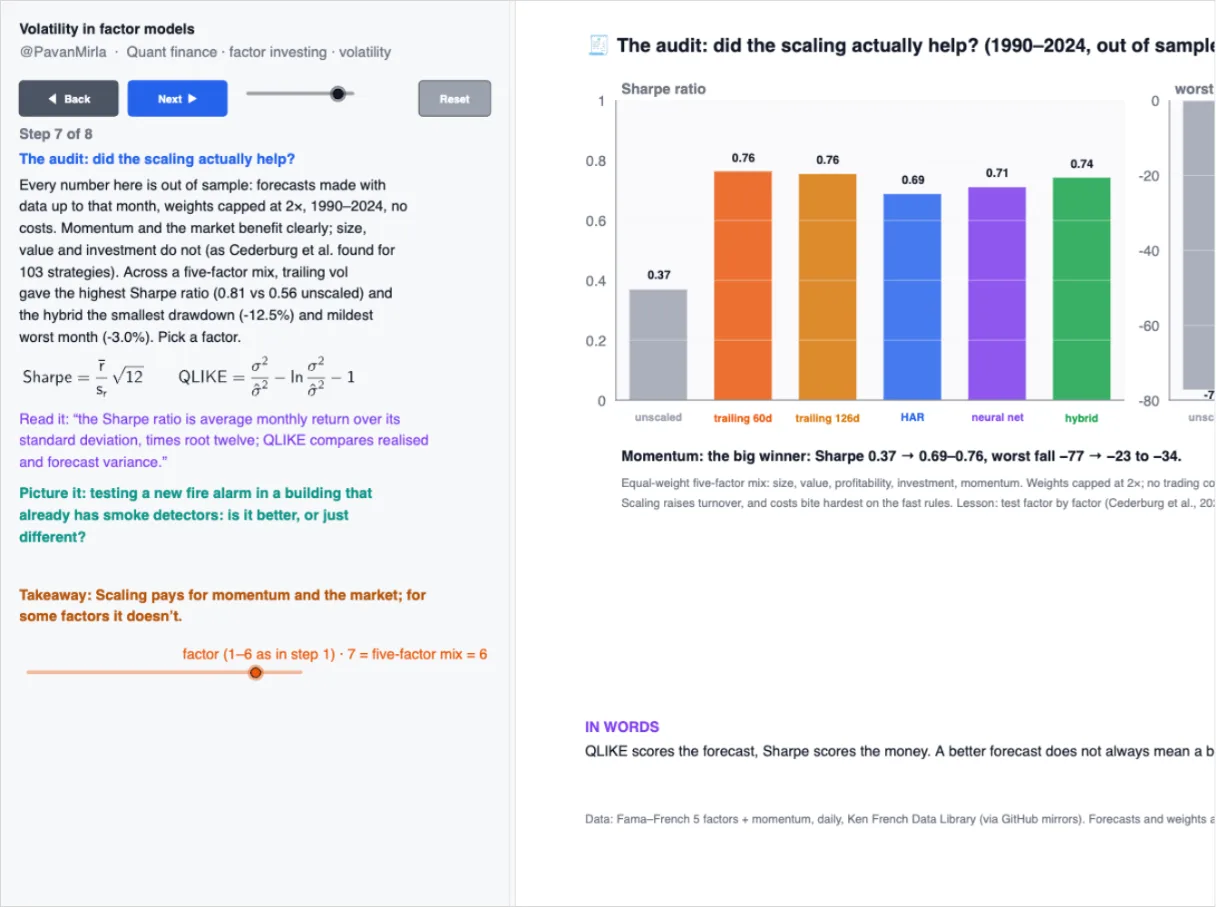
A solid introduction to factors as long–short portfolios (Fama–French five plus momentum, daily since 1963), then why they crash: momentum’s huge drawdowns in the 2009 crisis and in 2020. Compare traditional trailing-volatility scaling, statistical HAR forecasts and a neural net whose non-linearity lets it learn regimes, and see why a HAR backbone with an AI overlay is the hybrid to use.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.