The lognormal world
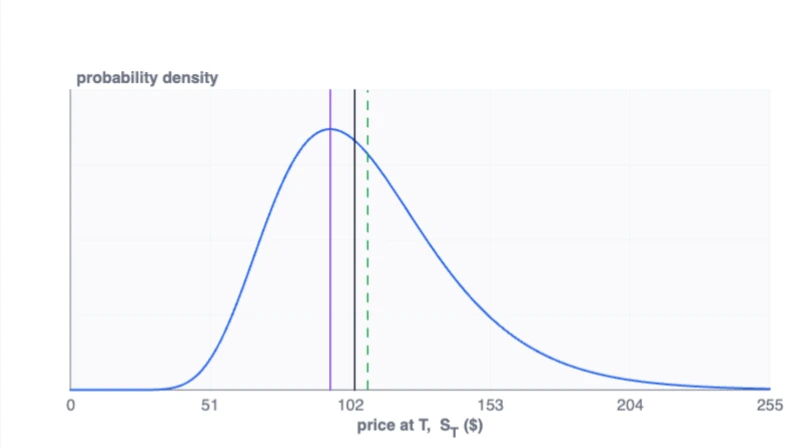
Start with a machine that multiplies today’s price by a positive random growth factor each day. Connect many possible journeys to the normal log-return bell and the right-skewed price density.
Follow eight paced Zon and Coach conversations about price probabilities, lopsided bands, recovery from losses, expected option payoffs and risk-neutral pricing.
Reset examples match the interactive: S₀=$100, μ=8%, σ=30%, one year, strike $120 and risk-free rate 4%. QF004b follows with the density derivation.
Explore next
- Quant Finance learning path
- QF004b: derive the density formula
- Integrals and expected payoff
- Continue to Black–Scholes
Stories, illustrations, and interactive mini lessons. Ask a question.