Where the lognormal formula comes from
A Quant Finance extension after The lognormal world and before Black–Scholes. Follow Zon and Coach from the normal log-price bell to the dollar-price density, one small step at a time.
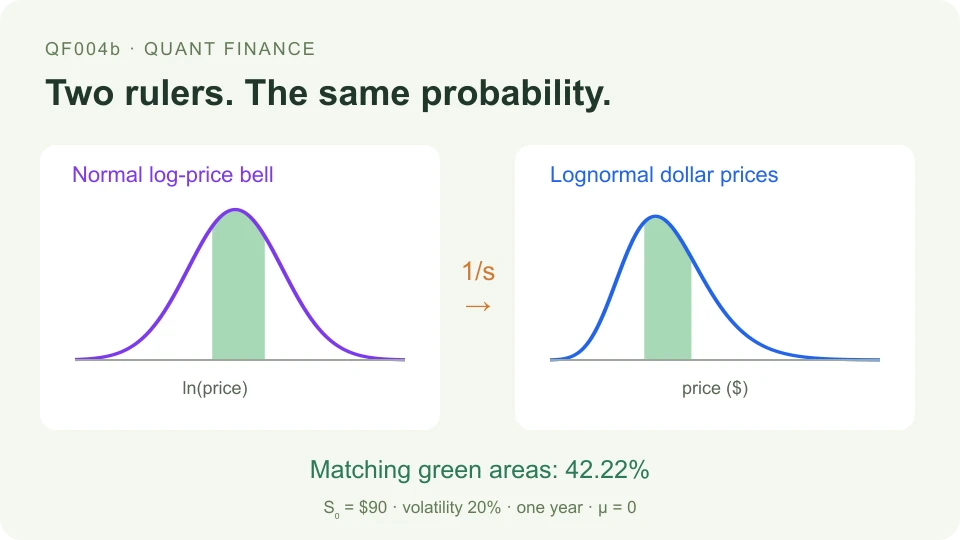
Compare two rulers, check matching probability areas, explore the 1/s conversion and distinguish mode, median and mean. Formula meanings, symbol definitions and a collapsed written guide support the interactive.
This premium lesson uses the existing request-access flow. Reset defaults use a $90 stock price, 20% volatility, one year and zero drift.
Explore next
- Quant Finance learning path
- Start with The lognormal world
- Apply it in Integrals and expected payoff
- Continue to Black–Scholes
Stories, illustrations, and interactive mini lessons. Ask a question.