Binomial trees to Black–Scholes
Start with a stock that can finish at $120 or $80, then build a call payoff from half a share and a loan. Zon asks questions, describes the diagrams, reads formulas and confirms the pricing argument with Coach.
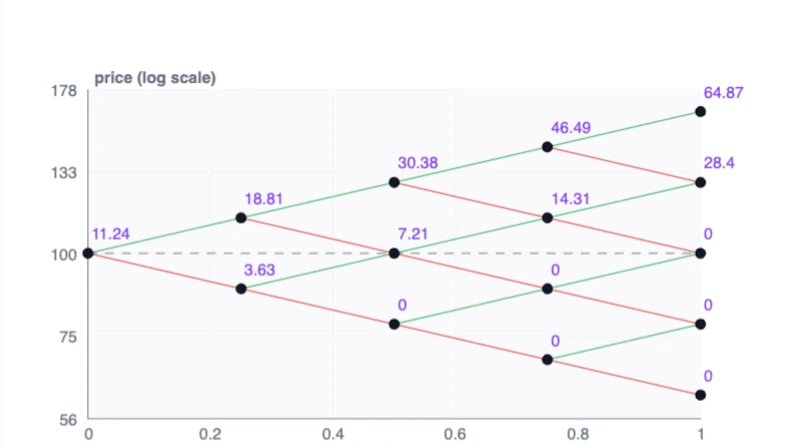
Explore forecast p versus pricing q, no-arbitrage, backward valuation, converging tree prices and the risk-neutral lognormal endpoints. Nine paced audio scenes follow the interactive.
The opening example uses simple one-year interest; the refined tree uses continuous compounding. The lesson states the trading assumptions and explains why continuous replication requires rebalancing.
Explore next
- Quant Finance learning path
- QF004: the lognormal world
- QF004b: derive the density
- QF006: rebalance the hedge
Stories, illustrations, and interactive mini lessons. Ask a question.