The arithmetic of active management
QE006 · Quant Equity Investing · Module 6 of 8. Thirteen interactive steps, each with its own guided explanation.
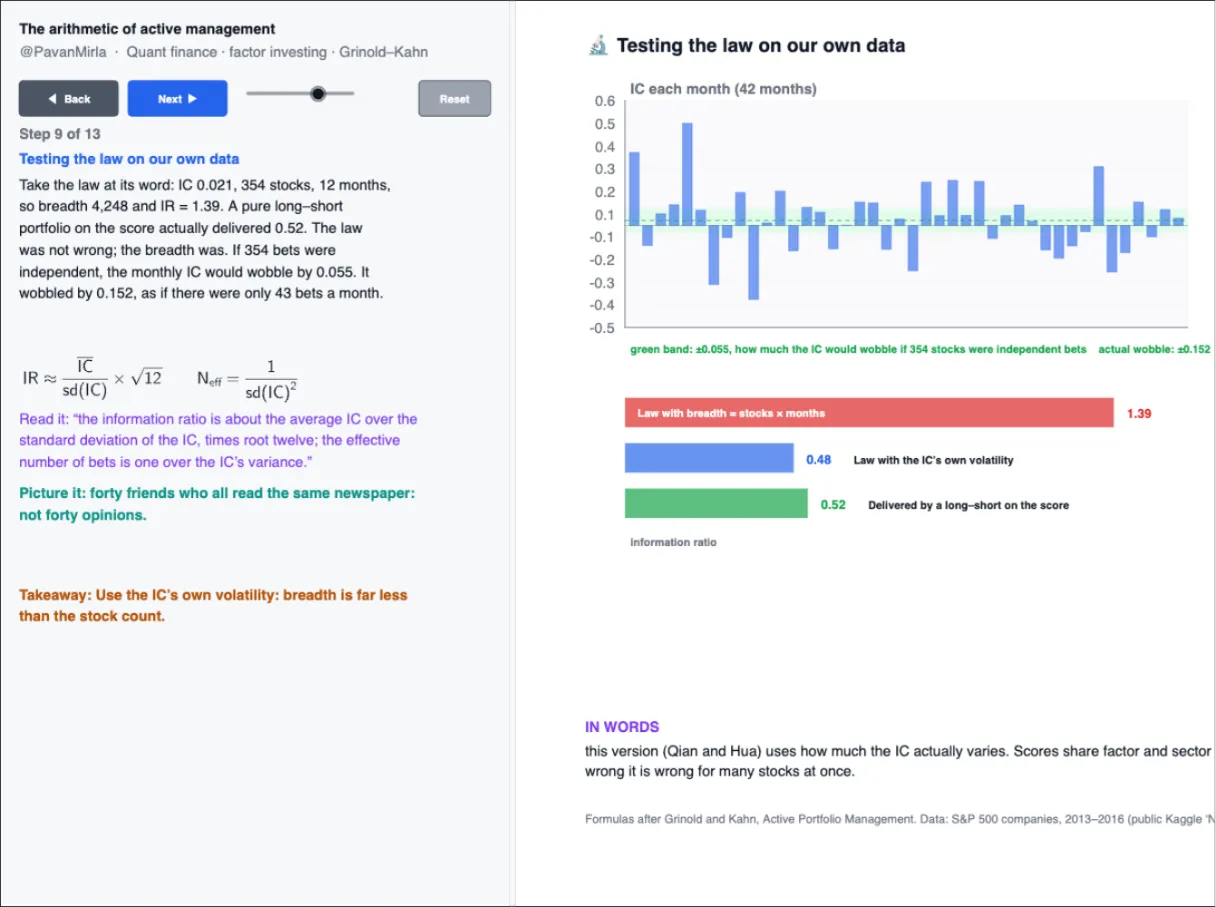
Grinold and Kahn’s arithmetic, computed on real S&P 500 portfolios: active return and tracking error, alpha and beta, the information ratio, value added, the information coefficient and the fundamental law. Then test the law on our own data: it promises an information ratio of 1.39, and a long–short on the score delivered 0.52. See why breadth is far less than the stock count, and what the transfer coefficient, combining signals and costs take away.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
- Quant equity investing: the lesson path
- Quant Equity Investing: from a score to a portfolio bootcamp
- VF006 · Volatility in factor models
Stories, illustrations, and interactive mini lessons. Ask a question.