Black–Scholes
SC006 · Stochastic Calculus · Chapter 6 of 6. Twelve interactive steps with a paced, recorded Coach–Zon conversation.
Derive the pricing PDE, interpret risk-neutral probabilities and test the limits of discrete hedging and constant volatility.
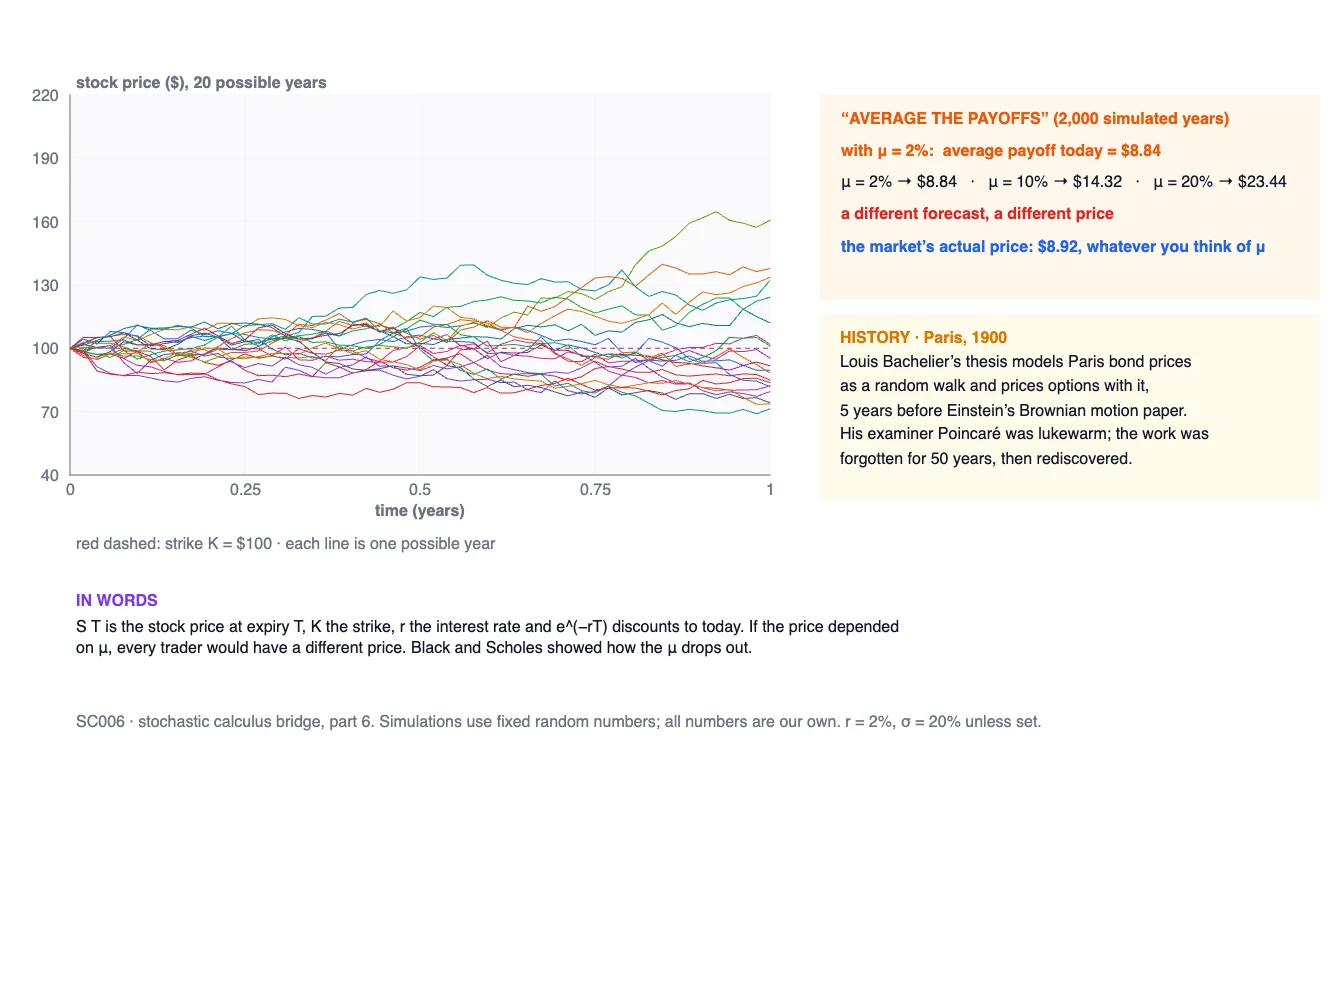
Make a prediction, change a control, read the formula and explain what changed. This is a model-based mathematical lesson, not a forecast of market returns.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.