Portfolios, correlation and the Sharpe ratio.
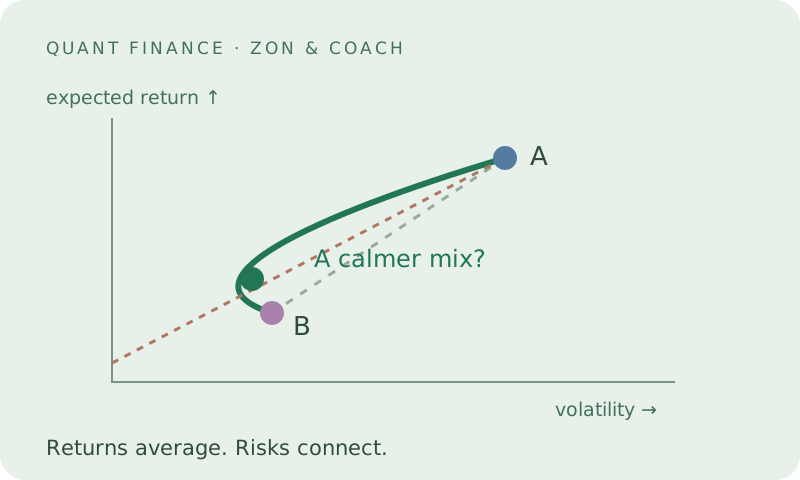
Start with two businesses and discover why expected returns average directly while volatility depends on how return surprises move together.
Eight narrated steps introduce the minimum-volatility mix, diversification with many assets, Sharpe and the highest-Sharpe allowed risky portfolio. Explore the risk–return curve and a rotatable 3D volatility surface.
Predict before changing the controls, use a hint when needed, and explain the picture in your own words. Model assumptions remain visible, including the limits of time-based Sharpe illustrations. This is education, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.