GK001 Delta
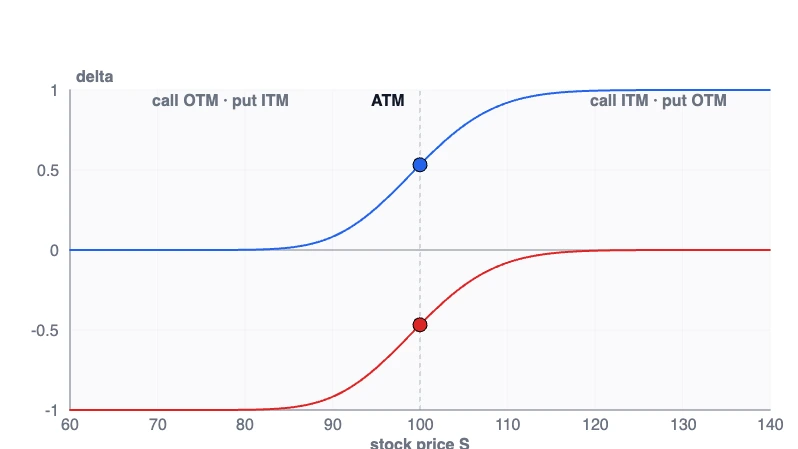
Delta measures the local change in option value when stock price changes and other inputs stay fixed.
Compare calls and puts, approach expiry, change IV, translate delta into shares and distinguish delta from risk-neutral ITM probability.
European non-dividend Black–Scholes examples with a 100-share contract multiplier. Sensitivities are not guaranteed outcomes.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.