Statistics for quant investing
QE001 · Quant Equity Investing · Module 1 of 8. Fourteen interactive steps, each with its own guided explanation.
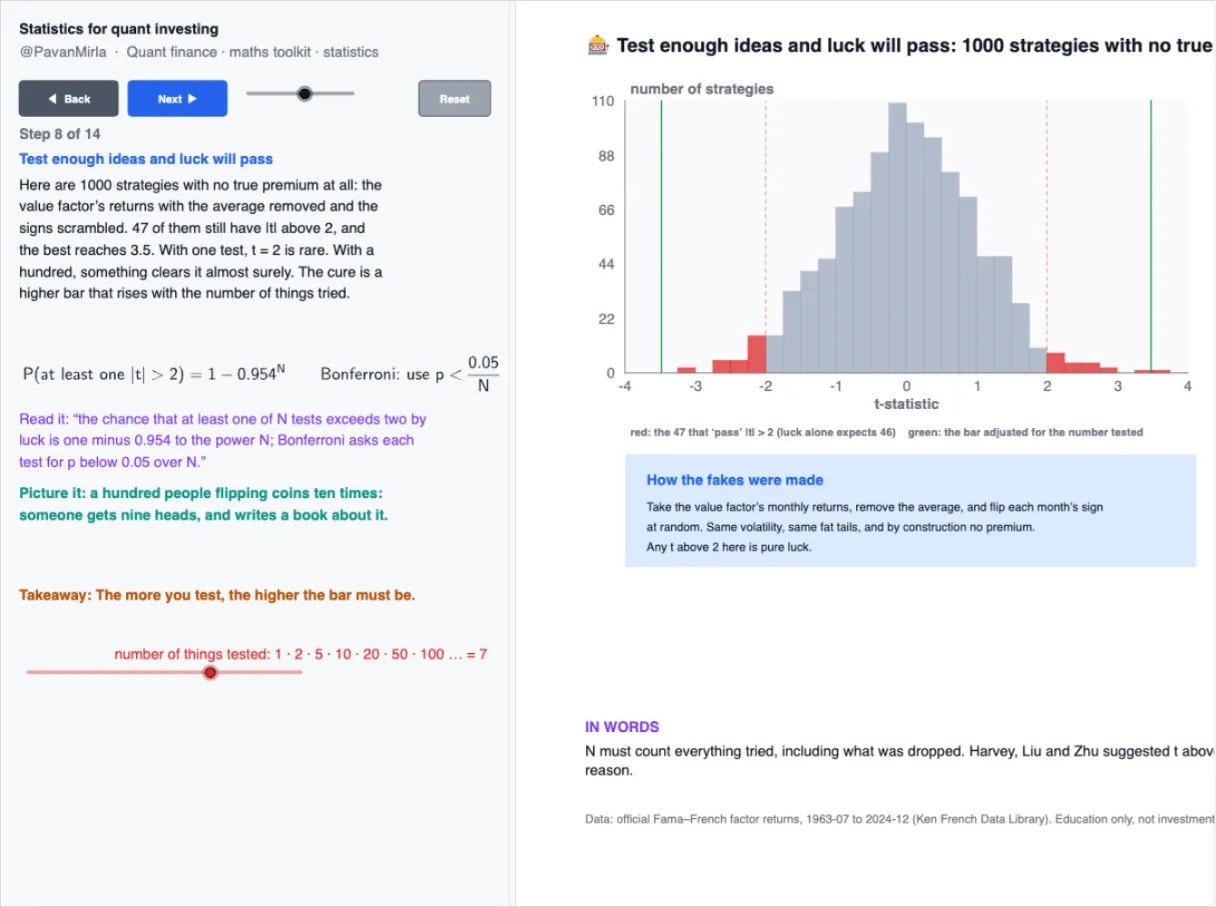
Every number in a factor study is an average of noisy returns. Build the toolkit to tell skill from luck on 738 months of official Fama–French factor returns (1963–2024): standard errors, the central limit theorem, t-statistics and p-values, how many years a claim needs, why testing many ideas lets luck pass, fat tails, unstable correlations, estimation error, and shrinkage as Bayes.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.