Refining alphas
QE004 · Quant Equity Investing · Module 4 of 12. Twelve interactive steps, each with its own guided explanation.
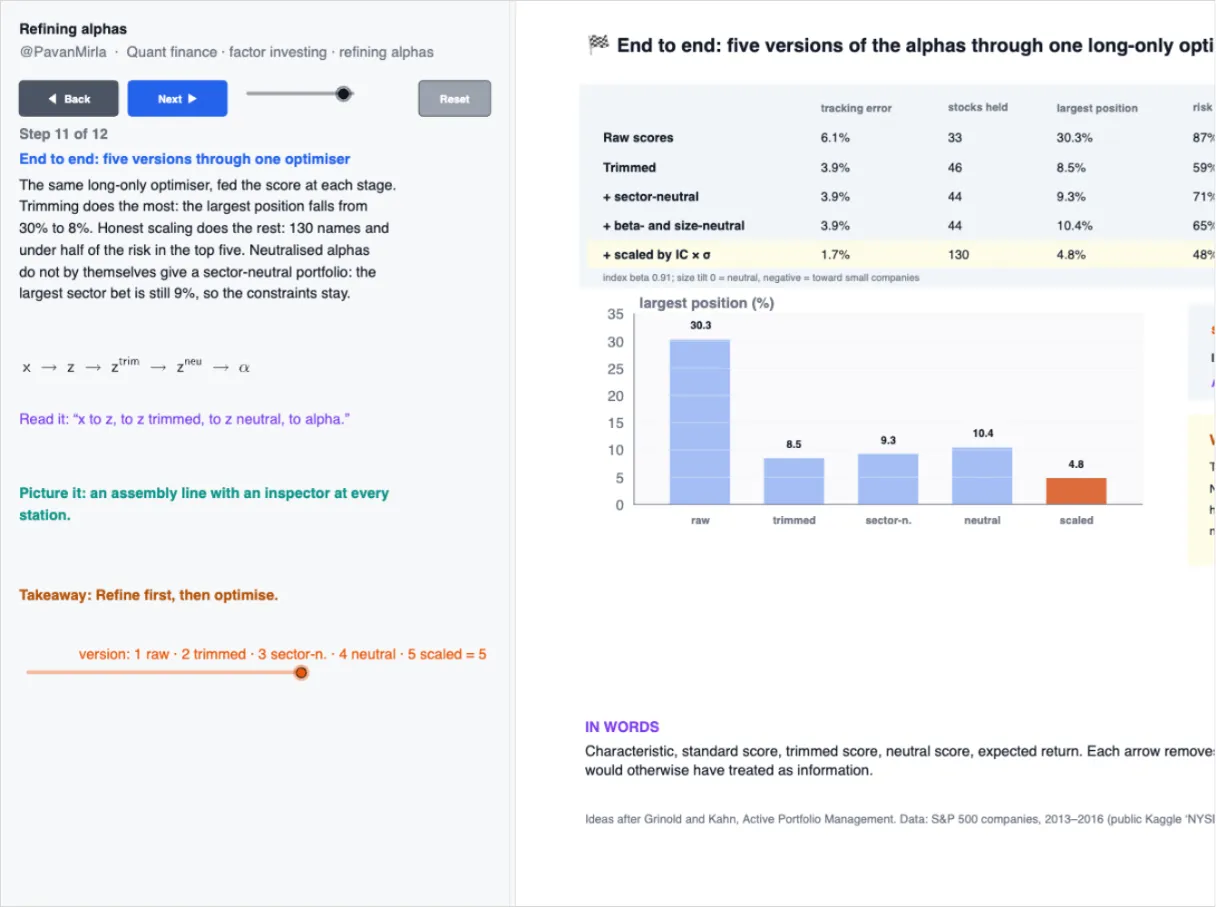
A raw score is not yet an expected return. Run each of Grinold and Kahn’s refining steps on 410 real stocks and measure what it changes: trimming the outliers that would put half the fund in two stocks, neutralising sector, beta and size bets, keeping the benchmark alpha at zero, and scaling a score into a return with IC × volatility. Finish with five versions of the alpha through one optimiser.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.