Optimiser Lab
QE013 · Quant Equity Investing · The capstone. Nine steps through a working optimiser, and eight experiments to run on it.
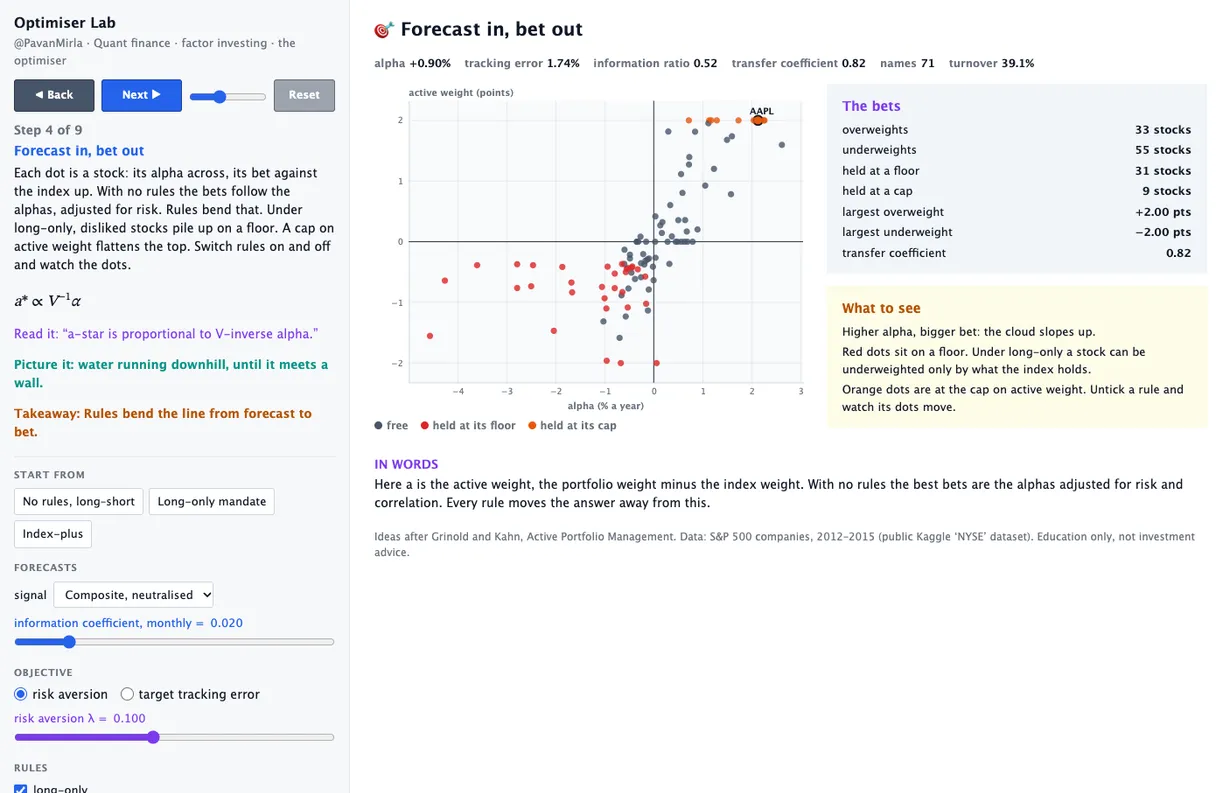
The capstone: a real mean-variance optimiser with a factor risk model, running in your browser on the 100 largest US stocks. Turn scores into alphas, read the risk model, switch on long-only, sector and turnover rules, see what each rule costs as a shadow price, and ask why the optimiser chose each weight. Then run eight guided experiments on six dates, from June 2013 to December 2015: the price of long-only, overconfidence, trading costs, and why risk is easier to forecast than return.
The eight experiments: 1. The price of long-only; 2. More risk, more damage; 3. Every rule has a price; 4. Overconfidence; 5. Risk is easier to forecast than return; 6. Trading costs slow you down; 7. One year proves nothing; 8. Six months later.
A teaching model on real US stocks, on six overlapping dates. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.