Matrix algebra for quant investing
QE002 · Quant Equity Investing · Module 2 of 8. Fourteen interactive steps, each with its own guided explanation.
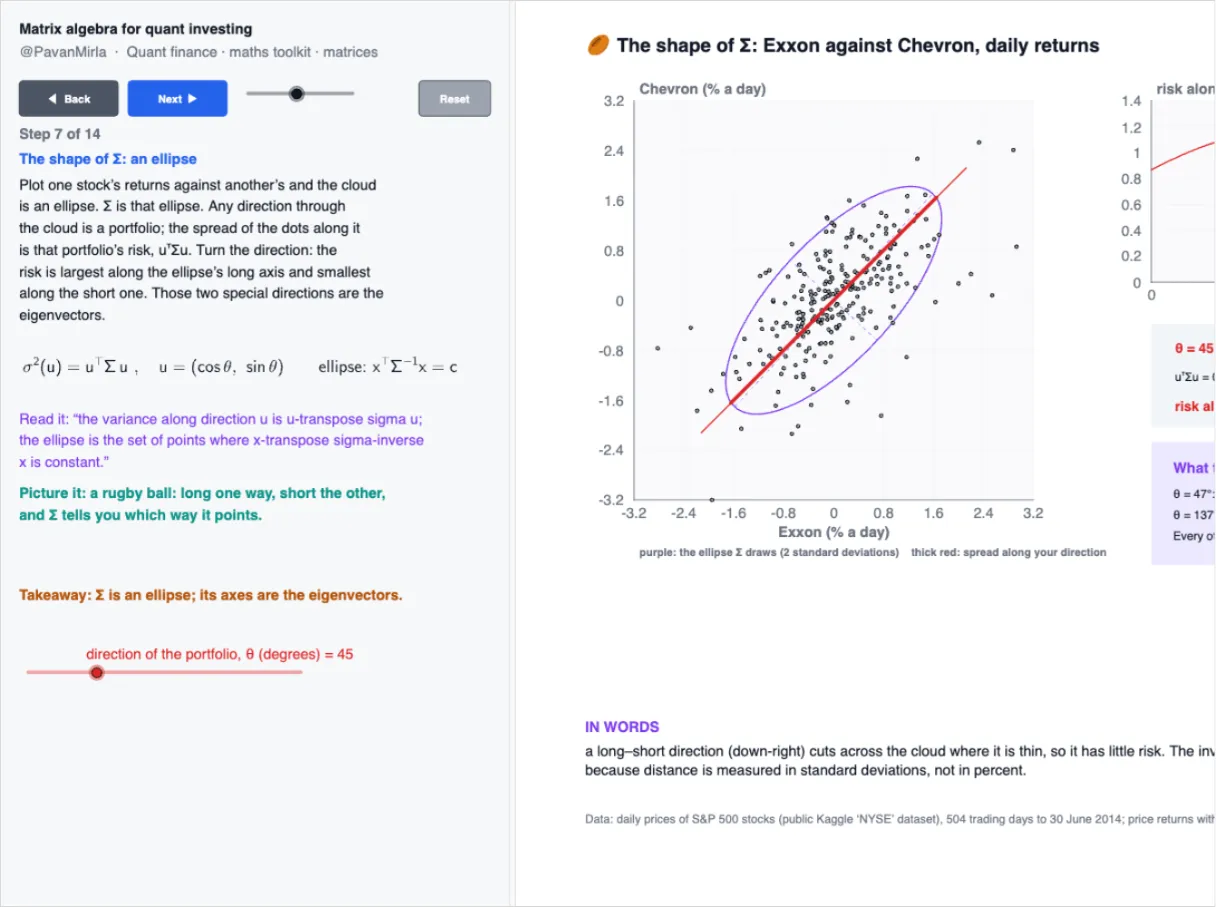
The grammar for combining weights, returns and risk, built on three real stocks (Exxon, Chevron and Apple) with numbers you can check by hand: the dot product, the covariance matrix, Σw and portfolio variance, the diversification curve, eigenvectors and PCA, the inverse and optimal weights, conditioning, Cholesky, and regression as the same algebra.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.