How factors are built
QE003 · Quant Equity Investing · Module 3 of 8. Twelve interactive steps, each with its own guided explanation.
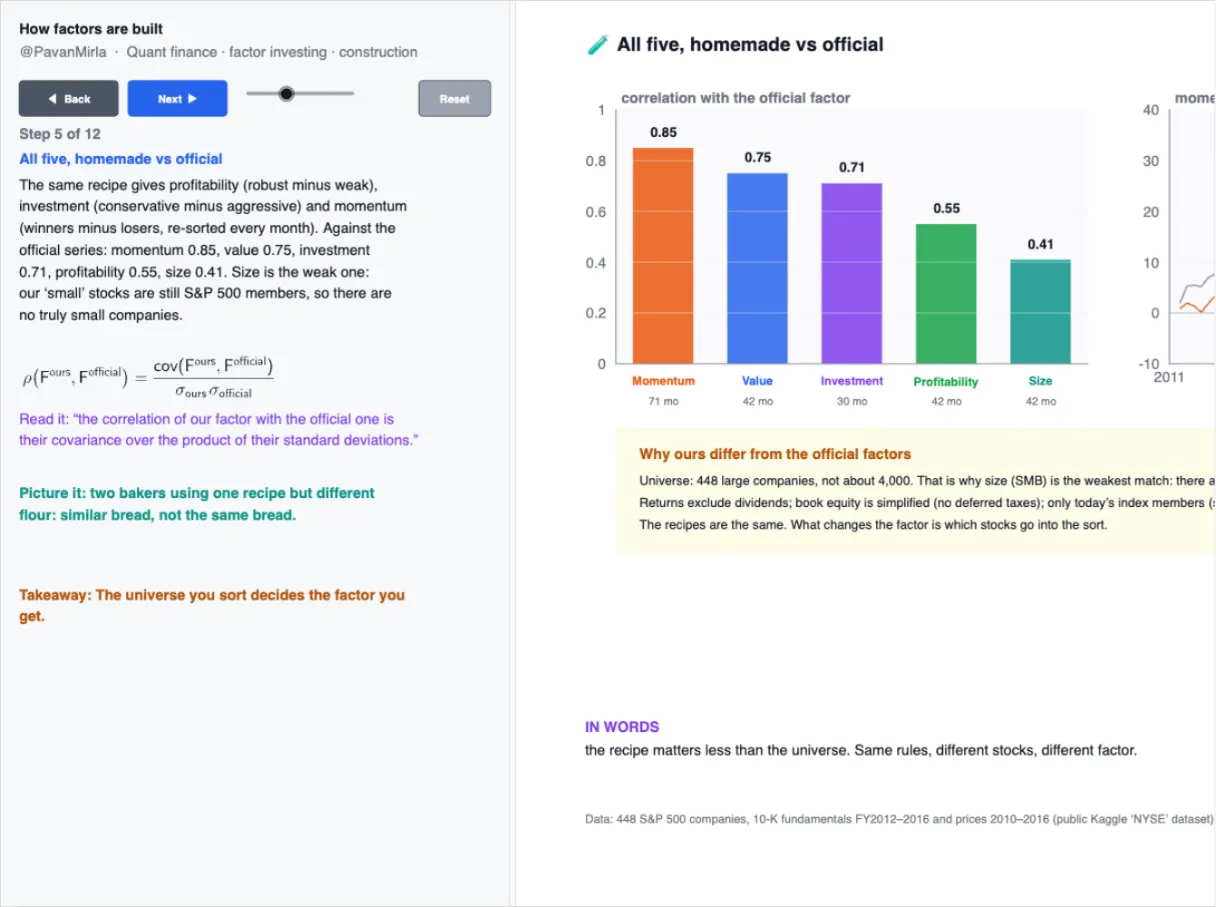
A factor is not found, it is built, and every step is a choice. Build five factors from scratch on 448 real S&P 500 companies: from 10-K filings to characteristics, the six-box sort, long–short factor returns, and homemade against official Fama–French. Then time-series and Fama–MacBeth regressions, pure factor returns and the risk model, the factor zoo, and risk premia across asset classes.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.