From scores to a portfolio
QE005 · Quant Equity Investing · Module 5 of 8. Thirteen interactive steps, each with its own guided explanation.
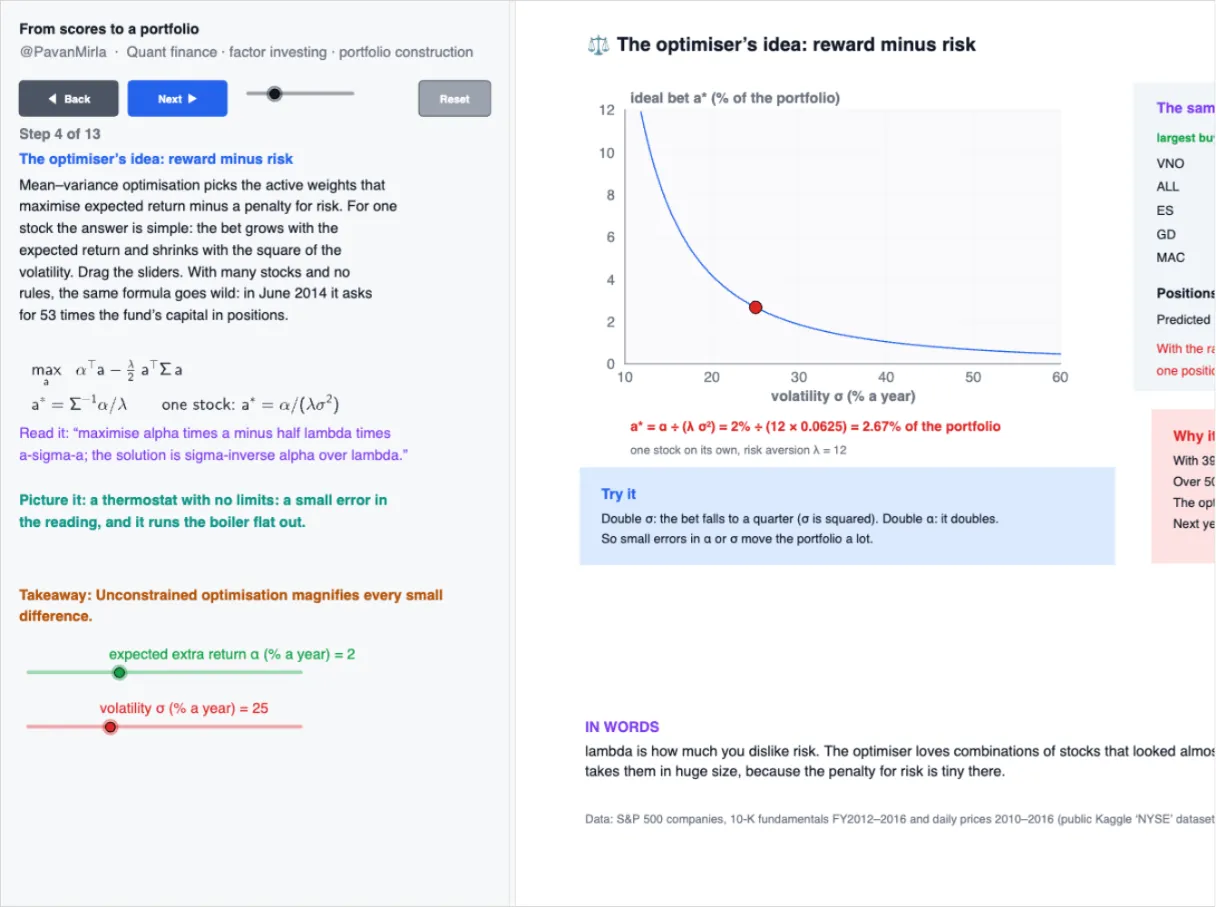
Walk the whole chain on real S&P 500 companies: one score from four characteristics, the naive top-fifth portfolio and the bets that came along for the ride, the optimiser’s reward minus risk (unconstrained, it asks for 53 times the fund’s capital), shrinkage and factor risk models, constraints and the transfer coefficient, turnover and the no-trade band, and 42 months out of sample, gross and net of costs.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.