Backtesting done right
QE007 · Quant Equity Investing · Module 7 of 8. Fourteen interactive steps, each with its own guided explanation.
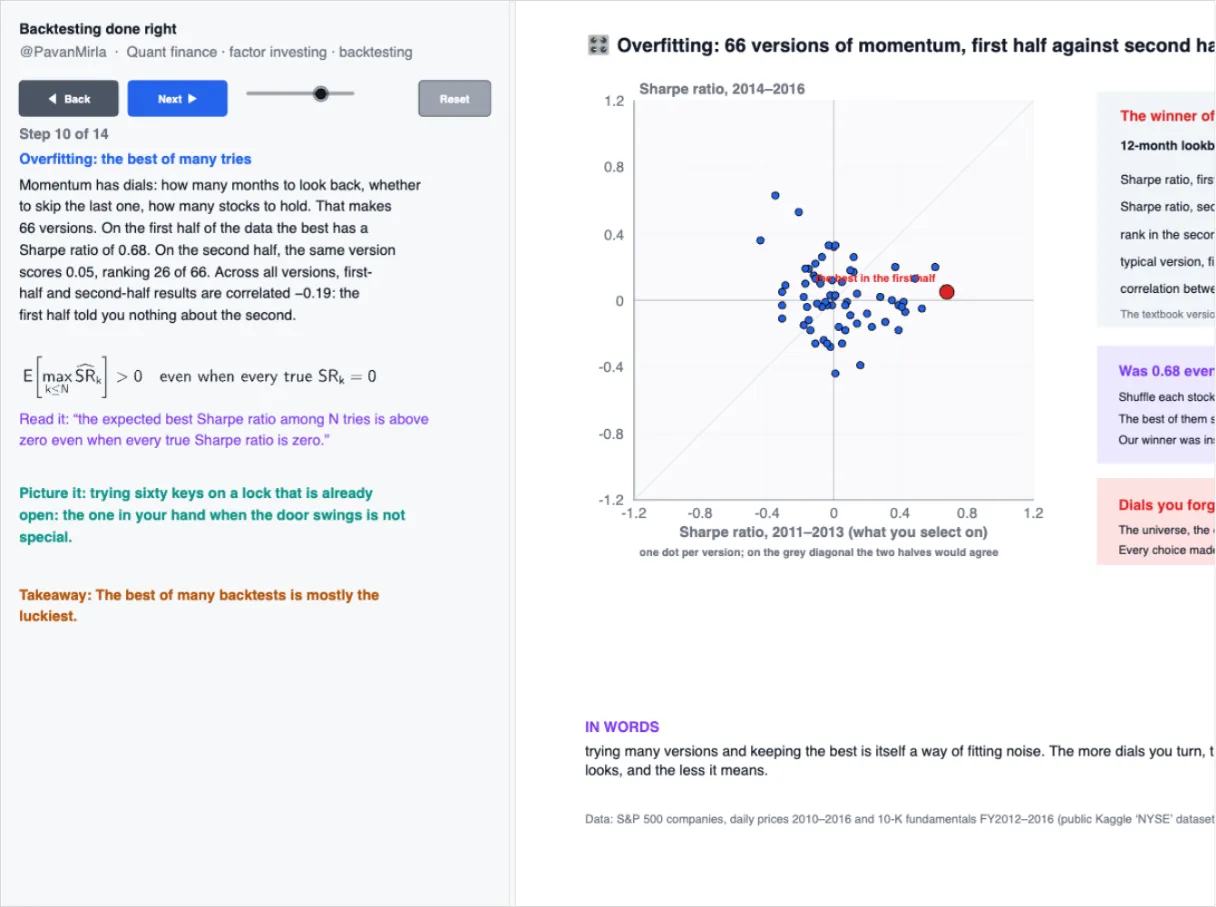
A backtest replays the past knowing things nobody knew then. Measure eight leaks on real S&P 500 data, then the cures: look-ahead from filing dates, the off-by-one signal that reports a Sharpe ratio of 4.7, a universe chosen with hindsight, restated data, unadjusted prices, trade timing, costs, and overfitting across 66 versions of momentum. Finish with walk-forward selection, the Sharpe haircut and an eight-test audit.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.