Alternative factor models
QE008 · Quant Equity Investing · Module 8 of 8. Eleven interactive steps, each with its own guided explanation.
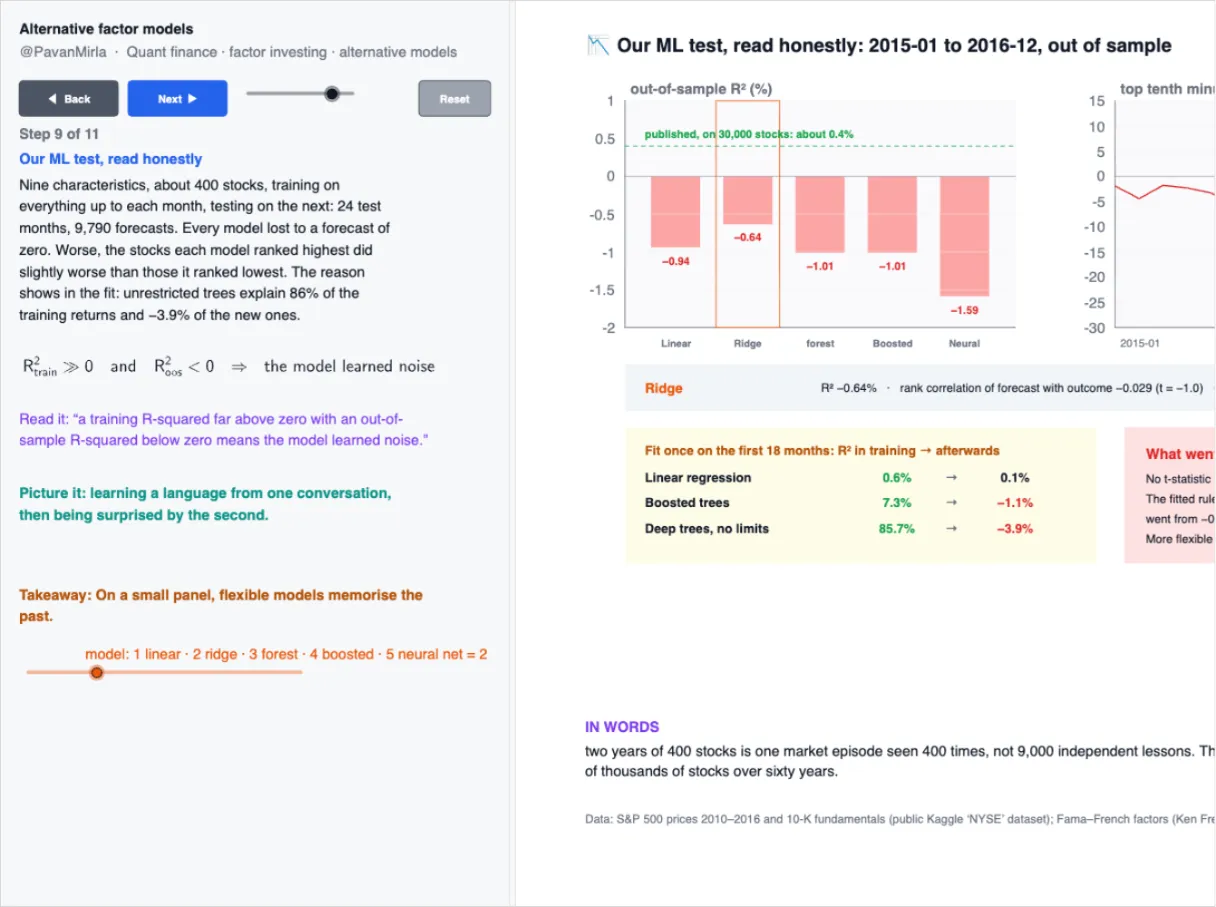
Four ways to build a factor model, compared on the same S&P 500 data: statistical factors from PCA and whether they hold up out of sample, one scoreboard for explaining risk, the q-factor model derived from how firms invest, spanning tests between models, machine learning read honestly (every model lost to a forecast of zero), and instrumented PCA, where betas follow the company.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.