Advanced forecasting
QE011 · Quant Equity Investing · Module 11 of 12. Eleven interactive steps, each with its own guided explanation.
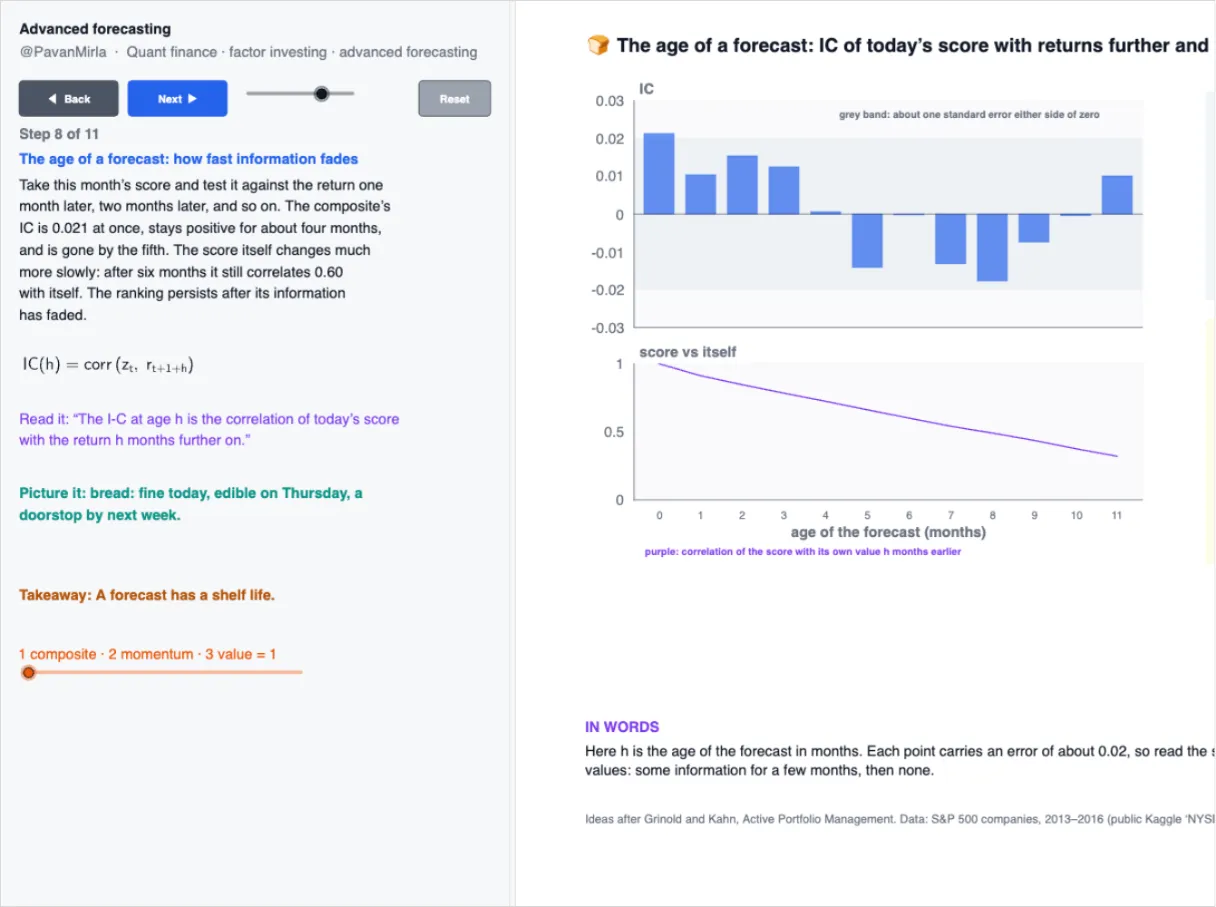
The basic rule turns one score into an expected return. Real work has several signals: some stronger, some repeating each other, some fresh and some months old. See the rule as a regression line, match the IC to its horizon, weight signals by strength and overlap, watch fitted weights flip between halves of the data, compare cross-sectional and time-series scores, measure how fast a forecast fades, and set the rebalancing interval against trading.
Every step uses real market data. This is education about models and their assumptions, not financial advice.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.