Why one week of risk is so noisy
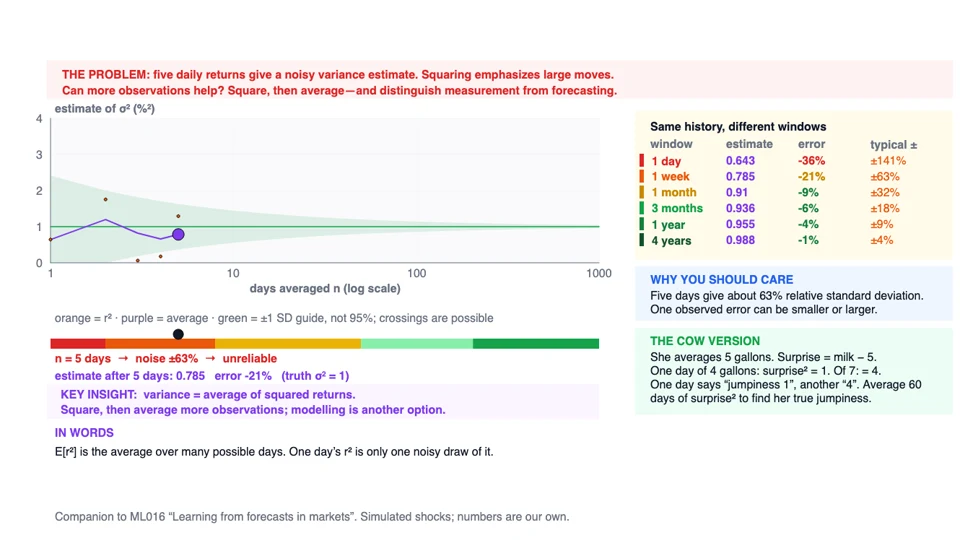
Derive the noise of a variance estimate from squared shocks, averaging, chi-square shapes and kurtosis—then connect measurement to risk forecasts.
A simulated teaching example with formulas, symbol definitions and paced Zon–Coach conversation. Separate measurement uncertainty from forecast bias and information leakage.
Explore next
Stories, illustrations, and interactive mini lessons. Ask a question.